Category: ΝΕΑ ΕΞΩΤΕΡΙΚΟΥ

12
Σεπ

IMF Looking For ‘Improved Communication’ From Argentina: Lagarde

IMF Looking For ‘Improved Communication’ From Argentina: Lagarde

By Patrick Gillespie

(Bloomberg) — 

International Monetary Fund Director Christine Lagarde told the Financial Times in an interview her institution is looking for Argentina’s central bank to have “clarity, transparency, proper and due information to market operations and improved communication.”

  • Argentina’s new austerity measures are key determinant of the fiscal policy, Lagarde said
  • IMF still considering Argentina’s request for a rephasing of payments from $50 billion credit line
  • Improved monetary policy communication would have a significant impact on Argentines’ confidence, Lagarde said
  • Lagarde is focused on protecting Argentina’s most vulnerable citizens from austerity measures
  • Argentina has about 0.2% of GDP available, if needed, to protect vulnerable citizens
    • “If President Macri includes serious reforms in his plan then we will look at it, we will assess the impact on the macroeconomic situation in Argentina, determine the debt sustainability and work with them”


12
Σεπ

More Than Half of Argentines Wouldn’t Vote Macri in 2019: Poll

More Than Half of Argentines Wouldn’t Vote Macri in 2019: Poll

By Patrick Gillespie

(Bloomberg) — 

52.9% of Argentines wouldn’t vote for President Mauricio Macri if he chose to seek re-election in 2019, according to a poll by consulting firm Raul Aragon & Associates.

  • 30.8% of Argentines said they would vote for Macri
    • 16.3% say they are unsure whether they would vote for Macri
    • Poll did not ask who Argentines would vote for if they didn’t vote for Macri
  • 58.7% of Argentines say they don’t believe the government’s new measures will tame inflation
    • 20% say the measures will control inflation; 21.3% uncertain
    • Poll question does not specify which measures
  • 74.9% of Argentines say their personal economic situation has deteriorated somewhat, a lot or very much in the last 30 days
    • 22% say personal economic situation has not deteriorated or only worsened a little in last 30 days; 3.2% uncertain
  • Poll conducted between September 5-8, after government unveiled new austerity measures and central bank hiked interest rates in late August
  • Aragon’s firm polled 600 people; margin of error +/-3.9%


12
Σεπ

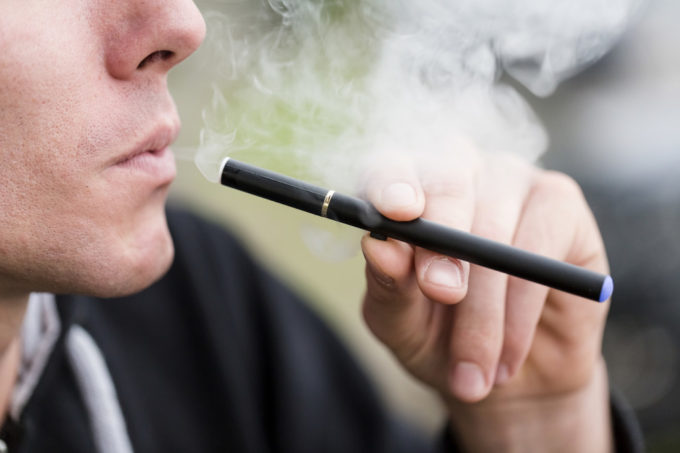
FDA Threatens to Pull E-Cigarettes to Fight Rise of Youth Vaping

FDA Threatens to Pull E-Cigarettes to Fight Rise of Youth Vaping

  • Agency asks five makers for plans to stop use by children
  • Commissioner Gottlieb cites an ‘epidemic’ of youth vaping
By Anna Edney

(Bloomberg) — 

The Food and Drug Administration is threatening to pull flavored electronic cigarettes like Juul off the market if the tobacco industry doesn’t do more to combat growing use of the products by children and teens.

FDA Commissioner Scott Gottlieb said the agency will soon release data that show a “substantial increase” in youth vaping this year compared with 2017.

“I have grown increasingly concerned around what we see as rising youth use in these products, and I’m disappointed in the actions the companies have taken to try to address this,” Gottlieb said in an interview.

The FDA told five major e-cigarette manufacturers Wednesday to come up with ways to address youth use in 60 days or the agency could require them to stop selling flavored products that appeal to children. The products being targeted are: Juul, Altria Group Inc.’s MarkTen, Fontem Ventures BV’s blu, British American Tobacco Plc’s Vuse and Logic.

To gain clearance to return to the market, the companies would have to prove that the benefits to adults who use e-cigarettes to stop smoking outweigh the risks associated with youth vaping.

“I certainly am in possession of evidence that warrants that,” Gottlieb said, adding that the problem has reached “epidemic proportion.” He declined to disclose the evidence.

Juul’s Popularity

Of the 3.6 million middle- and high-school students who said in 2017 they are current tobacco-product users, 2.1 million used e-cigarettes, according to the Centers for Disease Control and Prevention.

“There is no question that a lot of the youth use is being driven by Juul,” Gottlieb said.

Produced by San Francisco-based Juul Labs Inc., Juul devices resemble a USB thumb drive and have become popular among students. The company has more than two-thirds of the U.S. e-cigarette market, according to Nielsen data. The FDA is currently developing a survey to determine what percentage of youth vapers are using Juul products, Gottlieb said.

A nationwide sting operation from June through August resulted in more than 1,300 warning letters and fines to retailers who sold Juul products and other e-cigarettes to kids. It was “the largest coordinated enforcement effort in the FDA’s history,” according to the agency.

Read more: E-cigarette sting operation prompts warnings to retailers

Gottlieb recently began to ask whether the use of Juul and other similar products by kids is overshadowing any benefit to adult smokers using the devices to help them quit cigarettes. He said in June tobacco companies “better step up and step up soon” but he didn’t divulge what consequences the industry could face — until now.

In July 2017, the FDA said it was considering lowering nicotine levels in traditional cigarettes. In addition, the agency pushed back until 2022 a deadline for electronic-cigarette companies to submit applications to the FDA. Gottlieb said at the time he was trying to ease the regulatory pathway for products that are potentially less harmful sources of nicotine than smoking. Critics of pushing back the deadline raised concern that more kids would take up vaping.

Congress gave the FDA the authority to regulate tobacco products in 2009. The agency extended that reach to other tobacco products, including e-cigarettes, in August 2016 and allowed those products that were already on the market to continue sales while preparing an application for FDA clearance. The FDA is investigating whether some products on the market were introduced after the 2016 date and may need to halt sales, though didn’t name which ones may be violating the law.


11
Σεπ

Catastrophe Bonds Are Anything But a Disaster: Brian Chappatta

Catastrophe Bonds Are Anything But a Disaster: Brian Chappatta

Surging issuance protects insurers while investors reap profits.
By Brian Chappatta(Bloomberg Opinion) —

Leave it to catastrophe bonds to be among the most well-functioning debt markets out there.Issuance of “cat bonds” has climbed to more than $11 billion this year, about the same as this time in 2017, when sales hit a record, according to data compiled by Bloomberg. The debt helps protect insurers from potentially massive costs tied to damage from hurricanes, floods or other natural disasters. That’s important given that Hurricane Florence has strengthened into a Category 4 storm barreling toward the U.S. East Coast, with top winds reaching 130 miles (209 kilometers) an hour.

Now, you might think cat-bond buyers would be panicking. After all, Florence is shaping up to be of similar strength as Hurricane Hugo in 1989, which came ashore near Charleston, South Carolina, and caused about $14.1 billion in damage when adjusted for inflation, making it the 13th costliest U.S. storm. The entire purpose of cat bonds is to set aside proceeds to help pay future disaster claims, if needed. That’s money that investors won’t get back.

But that’s not what’s happening in this sliver of the financial markets. In fact, the bonds have gained 4.3 percent this year as measured by the Swiss Re Cat Bond Total Return Index. They’re up a remarkable 20 percent from 12 months ago, bouncing back from the index’s steepest loss on record in the wake of a devastating month for Atlantic hurricanes. In fact, as Bloomberg News’s Michael Regan pointed out, cat bonds haven’t posted a negative annual return since the index began in 2003.

So issuers are well protected and investors are well compensated. What’s the catch?

Certainly, a huge storm that activates so-called trigger events on a wide swath of securities would devastate investors. And their buffer is shrinking as the market matures — the average coupon on a cat bond issued this year is a mere 5 percent, Bloomberg data show. The average expected loss, according to a report from Brendan Grady at KeyBanc Capital Markets, is 2.71 percent. Combined, the spread is the narrowest ever.

But for cat-bond investors, it’s not as simple a calculation as “storm = losses” and “no disaster = profit.” Grady explains it like this:

“Hurricane Harvey hit Texas and was the second costliest storm in U.S. history — however — there were no losses for catastrophe bonds other than the initial mark-to-market impact of the storm. … Part of the reason that investors are willing to take on these risks is that the bonds insure for very specific events. A bond may only cover wind damage for a Carolina Hurricane, but not flooding.”

This specificity works to the advantage of all parties. For bond buyers, it reduces the likelihood that their money will be diverted away to cover claims. For insurers, it’s not as if cat bonds are the only method of insulating themselves from losses. Rather, the debt is just another way to hedge against a once-in-a-generation type of disaster.

Still, the market’s success has even surprised its experts. Consider Michael Millette, former head of structured finance at Goldman Sachs Group Inc., who helped the bank develop a market for cat bonds in the 1990s. He said in a Bloomberg Businessweek article in January that the market “exceeded my expectations as far as resiliency” in 2017. After a rash of hurricanes, “losses were consistent with the losses that investors felt should have occurred.”

The other upside for buyers is that these bonds have little to do with the overall economy and business cycle. That makes them a strong candidate for diversification among the typical “sophisticated investor” crowd — pensions, endowments, family offices and hedge funds.

As cat-bond sales this year have shown, supply has kept up with demand. And, according to a report from Kroll Bond Rating Agency, “many observers agree this will continue as it is expected there will be a greater need for more insurance due to climate change.”

According to Kroll, 2017 generated the most disaster damage in the history of the insurance-linked securities market. And yet it’s as strong as ever. Ironically, Kroll says the decline in credit ratings on these transactions — down to 27 percent of volume since 2013 from 75 percent previously — signals that investors are comfortable with the risks embedded in cat bonds. They simply don’t need to rely on the agencies’ input anymore after they have seen how this debt performs in bad times.

For the superstitious, this is the time to knock on wood. Insurers and investors alike would prefer no disasters at all, particularly one like Florence that could be in the same mold as Hugo, which killed 49 people in the U.S. and across the Caribbean. Total return seems inconsequential when people’s homes are destroyed.

But the cat-bond market is specifically designed for if and when disaster strikes. And at least for now, it seems built to last.

6
Σεπ

Italy’s Finance Minister Sees Wider Than Expected Budget Gap

Italian Finance Minister Giovanni Tria has accepted that weak economic growth and the government’s populist program mean that the 2019 budget deficit may need to widen more than previously anticipated, two newspapers reported Thursday.

Tria’s view is that the gap could rise to at least 1.5 percent of gross domestic product next year, newspaper La Stampa said, without saying where it got the information. That is higher than the 1.2 percent he previously predicted. Newspaper Il Messaggero said he could see a deficit up to 1.8 percent.

The latest reports highlight the struggle between Tria, a cautious academic, on the one side and the coalition partners Five Star Movement and League on the other.

Messaggero said the two parties are pushing for a 2019 deficit somewhere between 2 percent and 2.5 percent. A second top-level budget meeting is scheduled for today, where Messaggero says Tria has been asked to provide more information and solutions.

The figures reported in newspapers are still well below the 3 percent European Union limit, though markets have become increasingly worried about the constant uncertainty in Rome. Italy’s leaders have been whipsawing markets and the EU with contradictory statements all summer, pushing bond yields to a five-year high last week.

Barclays economists’ main scenario is for a deficit of 1.9 percent this year and 1.7 percent in 2018, according to a report late last month. While that would signal the government won’t allow a deterioration in the public finances of the size some had feared, slower consolidation “will set Italy’s debt equilibrium on an increasingly unstable path in the medium term,” it said in a research note.

3
Σεπ

Αργεντινή: Μέτρα λιτότητας πριν από το ραντεβού με το ΔΝΤ

Η κυβέρνηση της Αργεντινής θα ανακοινώσει σήμερα ένα πακέτο μέτρων λιτότητας, μία μέρα πριν από το κρίσιμο ραντεβού με το ΔΝΤ, με το οποίο ελπίζει να διορθώσει τη δημοσιονομική ανισορροπία που θεωρείται πως πυροδότησε τη νομισματική κρίση και την ελεύθερη πτώση του πέσο.

Συγκεκριμένα, ο υπουργός Οικονομίας και Οικονομικών Νικολάς Ντουχόβνε στη συνέντευξη Τύπου που θα παραχωρήσει σήμερα (17:45 ώρα Ελλάδας), αναμένεται να ανακοινώσει νέους φόρους στους τομείς των μεταλλείων, των ορυχείων, στις εξαγωγές σόγιας, αλλά και αρκετά ακόμη οδυνηρά μέτρα δημοσιονομικής προσαρμογής.

Σύμφωνα με την εφημερίδα Clarín, πριν από τη συνέντευξη θα προβεί σε τηλεοπτικό διάγγελμα ο κεντροδεξιός πρόεδρος Μαουρίσιο Μάκρι, για να ανακοινώσει ευρύ ανασχηματισμό. Από τα 22 μέλη του υπουργικού συμβουλίου, αναμένεται να απαλλαγούν από τα καθήκοντά τους τα 10.

Η κυβέρνηση θεωρεί προτεραιότητα τη μείωση του χρόνιου δημοσίου ελλείμματος, που τροφοδοτεί τον πληθωρισμό -ο δείκτης τιμών καταναλωτή αναμένεται να αυξηθεί με ρυθμό που θα ξεπεράσει το 30% το 2018- και καθιστά ευάλωτη την τρίτη μεγαλύτερη οικονομία της Λατινικής Αμερικής. Αφού κατάφερε να μειώσει το έλλειμμα από το 6% του ΑΕΠ το 2015 στο 3,9% το 2017, η κυβέρνηση μέχρι στιγμής προέβλεπε να το μειώσει στο 2,7% φέτος, στο 1,3% το 2019 και να καταρτίσει ισοσκελισμένο προϋπολογισμό το 2020.

Ο Ντουχόβνε θα βρεθεί αύριο Τρίτη στην Ουάσιγκτον όπου θα έχει συνάντηση με τη γενική διευθύντρια του ΔΝΤ Κριστίν Λαγκάρντ, προκειμένου να διαπραγματευθεί την αναθεώρηση των όρων της δανειακής σύμβασης που υπεγράφη τον Ιούνιο ανάμεσα στα δύο μέρη.

Παρά τη χορήγηση του δανείου των 50 δισεκατομμυρίων δολαρίων από το ΔΝΤ στην Αργεντινή -η πρώτη δόση του οποίου, ύψους 15 δισ. δολαρίων ήδη εκταμιεύθηκε και εν μέρει δαπανήθηκε- η κατάσταση για την ευάλωτη αργεντίνικη οικονομία συνέχισε να επιδεινώνεται. Το Μπουένος Άιρες ζητεί έτσι να επιταχυνθεί η εκταμίευση των δόσεων. Γι’ αυτό, προβλέπεται να δεσμευθεί ότι θα επιταχύνει τις προσπάθειες μείωσης του ελλείμματος.

Στο ίδιο πλαίσιο, η υποτίμηση του πέσο -πλέον κατά 50% φέτος έναντι του αμερικανικού δολαρίου- αναστατώνει και φοβίζει τους πολίτες στην Αργεντινή. Εξοικειωμένοι με τις οικονομικές κρίσεις, γνωρίζουν καλά πως όταν το πέσο πέφτει, ο πληθωρισμός απογειώνεται και η οικονομία επιβραδύνει. Η κυβέρνηση προβλέπει ύφεση 1% το 2018, έπειτα από την ανάπτυξη με ρυθμό που πλησίασε το 3% το 2017.

Πηγή: ΑΜΠΕ-AFP

3
Σεπ

Italian Finance Minister Says Spread Will Narrow on Budget Plan

Italy’s yield spread will narrow as budget details are unveiled over the next month, Finance Minister Giovanni Tria said in an interview with la Repubblica, coming in the wake of widening spreads and a decision by Fitch Ratings to lower its outlook on the country.

The eventual makeup of the Italian budget has been an investor focus all summer, with bond yields pushed higher in response to the new populist government’s expensive electoral promises. Those include hefty tax cuts and some form of universal income for the poor that could have a negative impact on the country’s debt and deficit.

Giovanni Tria

Tria hit back at charges the budget could go off the rails and breach agreed-upon European covenants including a deficit ceiling of 3 percent of gross domestic product. Despite wide-ranging promises made during the election season and seeming disagreements between coalition partners on priorities, “the government has an agreement on the confines of the budget” which will be respected. “By the end of September those commitments will become fact,” the minister said in the interview published Sunday.

‘Citizen’s Income’

Addressing concerns that the costly wish lists of the government’s two coalition partners — the rightist League, which favors a flat tax and the anti-establishment Five Star, whose program calls for a “citizen’s income” which critics have dubbed an expensive handout — Tria said that while all governments seek to build voter consensus through promises, “we have to judge by facts.” Voters, too know this, as “citizens have brains and the capacity to make judgments.”

The spread between Italian debt and German debt, which last week touched levels reminiscent of the financial crisis, will come down when budget details are unveiled, Tria said in the interview. “Budget stability will be respected,” the minister said. “The spread will narrow.”

The government is expected to set new public-finance and economic-growth targets by Sept. 27 and submit a draft budget to the European Commission by Oct. 15. On Aug. 20, Moody’s Investors Service extended a review of Italy’s credit rating to get “better visibility” on the fiscal path and reform agenda.

Italy’s current targets, agreed with the EU, see the deficit falling from 1.6 percent of GDP in 2018 to 0.8 percent in 2019, with a balanced budget in 2020. Tria told Bloomberg News in July that his aim is not to worsen the structural-budget situation and possibly to improve it. Still, he’s also said that slower-than-expected economic growth means the deficit is heading toward 1.2 percent in 2019.

The eventual end of the European Central Bank debt-purchasing program will be a “blow” to many countries, with the difference that Italy’s growth is “less strong.” Still, Tria insisted that Italy “isn’t fragile, it’s not the sick man of Europe”

1
Σεπ

How Poor Communication Fed Argentine Peso’s Collapse: QuickTake

A currency crisis is driving Argentina deeper into a recession. The peso is down more than 50 percent so far this year, competing in a race-to-the-bottom with the Turkish lira as the worst-performing currency in emerging markets. An emergency measure by the central bank, hiking interest rates to 60 percent from 45 percent, didn’t stop the peso’s plunge. Nor has selling reserves. Analysts say the lack of a clear, consistent strategy in South America’s second-largest nation is causing investors and the public to lose faith in the government of President Mauricio Macri.

Mauricio Macri

1. Why is the Argentine peso collapsing now?

Though Argentina’s economic problems have been building for a while, the recent collapse was triggered by disjointed and vague communication by elected leaders. On the morning of Aug. 29, Macri said the International Monetary Fund had agreed to expedite cash payments to Argentina as part of a $50 billion credit line. But IMF officials didn’t comment for several hours, and Macri’s government was mum on details of timing and amounts. Eventually, the IMF said only that it would considerArgentina’s request to speed up disbursements. The Fund’s Director, Christine Lagarde, will meet with the country’s Treasury Minister, Nicolas Dujovne, on Tuesday to discuss revisions to the agreement.

2. How did we get here?

A mix of bad luck, bad communication and confusing policies have plunged the peso in 2018. The central bank unexpectedly cut interest rates in January despite no signs that inflation was slowing down. That raised questions about whether Macri’s administration was controlling monetary policy, despite publicly saying the central bank was independent. Then a historic drought ruined the country’s top export, soy. Rising U.S. interest rates and emerging market selloffs in May and August compounded Argentina’s problems. And Argentinians appear unconvinced that Macri has the political will before next year’s election to cut spending faster and cover debt payments.

Luis Caputo, president of Argentina’s central bank, with Nicolas Dujovne in July.

3. Is default a possibility?

Despite concerns among some weary Argentines, the nation isn’t staring another 2001 in the face and shouldn’t default anytime soon, according to Martin Vauthier, an economist at Buenos Aires-based consultancy Eco Go SA. That’s because its repayment schedule is manageable over the next year and much of the debt is in pesos, not dollars, he said.

4. Is this similar to or different from Turkey?

The challenges are similar but the policies are night and day. Both countries have large fiscal deficits and large amounts of debt denominated in U.S. dollars. But while Turkey’s President Recep Tayyip Erdogan has unorthodox economic vies, Argentina followed the textbook recipe of hiking interest rates, selling reserves and cutting spending faster. Markets however, are taking a dimmer view on Argentina based on fundamentals, writes Tom Orlik and Felipe Hernandez from Bloomberg Economics. ”Argentina has a larger fiscal deficit and higher inflation than Turkey,” they note.

5. What’s the IMF’s role in all of this?

The $50 billion credit line it extended to Argentina in June was supposed to ease investors’ concerns about Argentina’s large deficits and debt load. It didn’t work, as the peso continued to decline. The IMF planned to disburse money gradually over this year and next, before Macri asked for much or all of it up front. Though Director Lagarde continues to express support for Macri, the IMF is a deeply unpopular institution in Argentina. It loaned billions to the country in December 2000 but didn’t come to the rescue when Argentina defaulted on $95 billion of debt in 2001 — at the time, the largest default by a country in history. The default led to an unprecedented economic crisis, wiping out one-fifth of the economy and causing poverty to soar. This is why Macri’s decision to return to the IMF has been poorly received in Argentina.

6. What else can be done to contain the peso?

With the benchmark interest rate now at 60 percent, the world’s highest, Argentina must turn to less conventional ways to remove excess money in the market. The central bank has sold billions worth of dollars at auctions to defend the currency, but that hasn’t done much good. What Argentina really needs, if it’s going to stop traders fleeing from its currency, is a quick narrowing of the budget deficit. Coming into this year, Macri sought to gradually cut spending. “A fiscal adjustment shock,” Goldman Sachs economist Alberto Ramos wrote in a note, is “the antidote for the market’s lost confidence.”

7. Where does Macri stand politically?

His approval rating hit a new low in August, according to the key index published by a university in Buenos Aires. And he faces a difficult choice. He needs to close the budget deficit faster to get markets on his side, but austerity will probably anger voters already feeling the pain of inflation that’s eroding wages. The big question is whether Macri can get a budget bill for 2019 through Congress with opposition support, then execute it without provoking widespread social upheaval ahead of nationwide elections scheduled for October 2019, during which Macri plans to see for another term.

8. Why does Argentina seem always in crisis?

It’s a country of ample natural resources but a history of poor governance. Political polarization over decades and a tendency to opt for short-term solutions has led Argentina to cycles of boom and bust. The 2001 default that plunged millions into poverty followed a successful run in the 1990s, when one peso was worth one U.S. dollar, which many economists at the time said was an unsustainable policy. These days, $1 equals about 38 Argentine pesos. The 2001 crisis was then followed by years of strong economic growth fueled by a global boom in commodities.

1
Σεπ

Argentina Is Said to Weigh Reinstating Taxes on Crop Exports

President Mauricio Macri is said to be considering reversing his flagship farm policy of cutting crop-export taxes as he tries to calm market fears over Argentina’s fiscal deficit.

Mauricio Macri

Argentina’s government is weighing reinstating a 10 percent tax on corn and wheat exports, according to a person with direct knowledge of the matter who asked not to be named because talks are ongoing and no decision has been made. The taxes may be published Monday in the government gazette, the person said. Press offices for the agriculture and treasury ministries declined to comment.

Under the plan being considered, the levies would be in place until the end of 2019, the person said. Taxes on raw soybean exports and on soy meal and oil would be frozen at current levels until the end of next year.

A truck piles wheat inside the storage facility in Sante Fe, Argentina.

Macri plans sweeping changes to restore confidence to markets as the economy enters the second recession in three years and inflation remains above 30 percent. Treasury Minister Nicolas Dujovne will unveil a new fiscal plan on Monday and will then travel to Washington to meet with International Monetary Fund officials to ask for money from a $50 billion credit line to be delivered more quickly.

Macri scrapped export taxes on corn and wheat when he took office in December 2015 as he turned to farmers to revive the economy. The farmers, in turn, lauded his rise to power after years of feuding with his predecessor, and planting soared. Macri also began reducing the tax on soybeans and soy meal and oil, made by crushing the beans.

“It’s not clear where they can rein in spending, so to close the deficit they’re going to have to suspend cutting taxes,” said Amilcar Collante, an analyst at La Plata-based economic research center CeSur.

Argentina is the world’s biggest exporter of soy meal and oil. The country’s crop shipments brought in $21.4 billion in 2017. After a crippling drought this year, production is set to rebound in 2019.

28
Αυγ

Italy Bond Yields Spike as Rome’s Budget Clash Stirs Echoes of EU Debt Crisis

Italy’s benchmark borrowing costs hit a four-and-a-half year high Tuesday as investors continued to trim government bond holdings amid concern that the country’s populist administration is on a collision course with EU officials in Brussels that echoes the worst of the region’s 2012 debt crisis.

By Martin Baccardax

Italy’s benchmark borrowing costs hit a four-and-a-half year high Tuesday as investors continued to trim government bond holdings amid concern that the country’s populist administration is on a collision course with EU officials in Brussels that echoes the worst of the region’s 2012 debt crisis.

Italy’s Deputy Prime Minister Luigi Di Maio told the Il Fatto Quotidiano newspaper Tuesday that his government could breach the EU’s 3% deficit target next year as it spends billions more than anticipated in order to meet various election commitments. The outlay is also expected to include billions more for improvements in Italy’s road and transport infrastructure following the deadly collapse of a busy commuter bridge earlier this month that killed 43 people in the northern city of Genoa.

Rome has also clashed with Brussels over the handling of migrants, mostly from Africa, landing on Italian shores as part of an overall crackdown on immigration by the right-of-center Interior Minister Matteo Salvini, who has accused the EU of shirking its responsibilities.

The clashes suggest the government, a coalition of the leftist Five Star Movement and the anti-EU League Party, could draft a 2019 budget plan that would add around €100 billion ($116 billion) to the country’s staggering €2.3 trillion debt pile and create a budget deficit that’s as high as 5% of GDP for the coming year, a figure that would be more than six times the previous target agreed with Brussels.

Capital flight from Italy accelerated in August. The morning the yield on 10 year govt bonds reached a new peak since the current administration was formed, hitting a 4.5 year high. All happening as Rome-Brussels relations deteriorating and ECB moves to wind down bond purchases.

The debate has pushed benchmark 10-year Italian government bond yields to 3.209% in early European trading Tuesday, the highest since March 2014, while Italy’s FTSE MIB stock index fell 0.85% to extend its decline since the new government was first established in late May to around 15%.

In fact, the extra yield, or spread, that investors demand to hold Italian government debt instead of paper issued by Spain, has risen to 1.76%, the highest since the peak of the region’s 2012 debt crisis. The spread to triple-A rated German bunds was quoted at 2.82% Tuesday, an astonishing gap in borrowing costs between the region’s first and third-largest economies

.
Italy’s swelling budget deficit — as well as its dangerously high debt-to-GDP ratio of 132% — suggest its 2018 growth rate of 1.2% could be difficult to achieve should investors dump domestic assets amid the ongoing tension between Brussels and Rome. Business sentiment in the manufacturing sector, for example, hit a 20-month low of 104.8 this month, according to ISTAT, Italy’s national statistics office, ISTAT, in data published earlier Tuesday.

Italy’s banks are also lumbered with more than €383 billion in government bonds, according to European Central Bank data published today, after having increased their holdings for each of the past seven months. Foreign investors, meanwhile, have dumped more than €58 billion in June and July.

Italy’s sovereign debt pile is more than €2.3 trillion, all of it denominated in a currency that it has to earn or borrow. That has made the pile nearly impossible to reduce, given the country’s poor productivity, which has contributed to three recessions since the global financial crisis in 2008.

However, for a host of reasons, global investors have either been insulated from Italy’s political and economic failings either by the European Central Bank’s myriad liquidity efforts or its vow to do “whatever it takes” to save the euro from an existential attack in foreign exchange markets.

That said, should contagion take hold and Italy’s bond yields rise to the 7.3% peak reached during the height of the region’s sovereign debt crisis in late 2011, European officials could be forced to deploy one — or both — of their most powerful backstops: the European Stability Mechanism (ESM) or the the ECB’s Outright Monetary Transactions (OMT).

The ESM, a centrally controlled rescue fund backed by around €700 billion in paid-in capital from Eurozone member states, has around €400 billion left over from previous loans to Greece, Portugal, Ireland and Cyprus and would likely fail to stablize markets should Italy’s $2.5 trillion economy require a significant bailout.

That could leave European Central Bank President Mario Draghi as Italy’s lender-of-last-resort.
Draghi is the principal architect of the Outright Market Transactions, or OMT program, an untested “bazooka” of central bank firepower that can buy unlimited amounts of government bonds in the secondary market in order to prevent an “unwarranted” tightening of any country’s fiscal mechanics.

This article was originally published by TheStreet

Comodo SSL